
21st July - Threats & Talks
Yesterday seemingly saw all parts of this Iran conflict play out in just one day. We began the day taking in the threats from the weekend and another night of US strikes on Iran, with markets seemingly trying to work out where to go from there. Then around noon UK time, we heard from an Iranian source that a proposal had been made by mediators for a cessation of strikes and a call to move back to a pre-July 9th stance when the MOU was still in effect. Markets rallied on the potential for strikes to stop and a path to peace could open up.
We then received the news that the Houthis were planning to implement a 'sea navigation ban' on Saudi Arabia, which could potentially impact shipping in the Bab al-Mandab Strait, one of the other main arteries for shipping from the Middle East out to sea. Later in the day, we then saw a social media post from Trump that said "Every time Iran kills an American soldier, they will pay for that killing many times over." This was then further reported on by Axios, who quoted a US official who said, "Trump will make Iran pay for the recent deaths of US soldiers. These devastating blows will continue until Trump deems otherwise, but talks between our countries are continuing." Within a few hours, markets heard of both an escalation and a de-escalation and seemingly were not sure which narrative would win.
Oil itself was one such market, with Brent dropping below $85 per barrel briefly before recovering back to $87 at the end of the day. Oil has been on a sharp upswing for the whole of the month; the price movements for the rest of the week will depend on which of the competing narratives the market believes over the coming days.

Forex
The uncertainty around the status of the conflicts in the Middle East was reflected in forex markets today, with the DXY rising to touch the 101.000 level for the first time since Wednesday last week. Markets were seemingly moving towards the USD as a safe haven option, though we will need to see if this continues for the rest of the week to confirm if it is more than just a temporary move to start the week. Should the escalations continue, then we would expect the USD to continue to receive support, but as the situation is down to two wildly unpredictable parties in the US and Iranian regimes, predicting the way the next few days will play out is close to impossible without inside information. As a result, it seems the smartest play is to be on the sidelines for the time being, until we have a more concrete idea of where each side stands.

The EUR and GBP continued to be relatively steady, with the GBP falling against the EUR a little yesterday as new Prime Minister Andy Burnham took office and announced his new Cabinet. He appointed John Healey as his new Chancellor instead of the rumored appointment of Shabana Mahmood, which caused the GBP to lose some demand. With the events elsewhere in the world, however, this was a small move. The real test that will affect the GBP moving forward will be the policies the new government implements and the market's reactions to them.
The AUD and NZD had another strong day, with both outperforming all other major currencies on the day, continuing their strength since the beginning of the month. The announcement of the potential continuation of discussions between the US and Iran will have helped, but the strength for these two seems to be coming from the fact the 'worst' has already happened in the war. Both markets do not rely solely on outside energy, so are impacted less by oil prices than competing currencies. The worst-case scenario for Iran was that the Strait of Hormuz would have closed and global demand would fall for all sectors. This has already happened, and the impact was a supply-side shock, meaning for the time being the AUD and NZD economies have only been hit with inflation increases. Whilst indices stay near all-time highs and demand for raw materials holds up, the Antipodean currencies will continue to perform well.
It is worth noting that overnight the NZD saw a slightly higher CPI print than expected, which will further strengthen the NZD's position over the coming weeks as rate hikes become more likely.

The CAD fell back yesterday on the potential news of talks continuing. Whether this becomes a longer reversal will depend on news from the Middle East over the coming days. The CHF and JPY both struggled yesterday, as they were hit with the double blow of losing some safe haven demand on the back of peace talk rumors, but also affected by oil prices not falling on the news to counteract this.
Indices
Indices were pushed lower by the uncertainty around Iran, but also by the continued selloff in the big tech and semiconductor names. The Nasdaq gapped 1.4% lower at the open to 25,525, then closed down 0.42% at 25,406. The Dow closed at 51,881, down 0.39%, with the S&P down just 0.05% at 7,440 — notably, it rose as high as 7,500 intraday before fading back. The story of the day was an attempted rally on peace talk news, before all of the indices fell in the afternoon session on uncertainty around the situation. The fact that the Nasdaq gapped lower before continuing down showed us that the tech sector is continuing to be under pressure, while the S&P staying flat seems to indicate that the rest of the market is absorbing the tech weakness rather than being dragged down by it. The balloon deflation theory is still holding strong for the time being. This week's earnings figures will be another test of whether the rotation is real or a quirk in the data.

Precious Metals
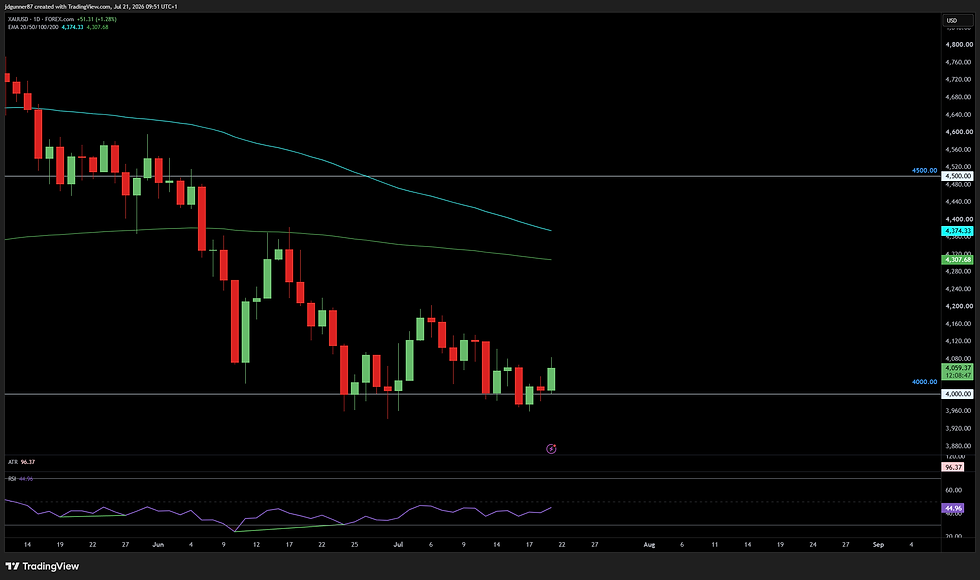
The metals markets were broadly steady on the day, seeing the same reaction as indices where they tried to rise but were pulled back by the end of the day. Gold was down 0.3% on the day to end at $4,007, while silver actually rose 1.4% to end at $56.40. The volatility in silver means this difference between the two metals is smaller than it looks, indicating variance rather than a significant difference in behaviour.
Metals remain in the same bind as they have been for months; they are solely reliant on interest rate decisions, and the safe-haven play is largely dormant. A tentative thaw in the Middle East could help, but we will need a longer-term change in inflation and FOMC commentary to see a meaningful recovery for metals.
Today's Market Drivers
GBP Claimant Count Change, 7 am UK time - This will give us an indication of the strength of the UK economy and will affect the GBP should we see a surprise.
AUD Unemployment, 2:30 am UK time Thursday - Another data release that will give us information on the health of the AUD economy and will contribute to future rate decisions.
Iran - As has been the case for a long time, word from Iran or the US will move markets as investors try to understand the situation and predict the direction of travel.
Comments