
14th September - FOMC Week Begins
The weekend was a relatively quiet one from a geopolitical perspective, but we did have a few things to note with regards to the Middle East conflicts. A vessel was struck in the Strait of Hormuz on Sunday, causing a fire onboard, so we are still seeing attacks on shipping traffic in the area. We also heard a senior government official confirm that there are no current talks taking place between the US and Iran, firming up the market expectation that the war is not close to being over. Oil has gapped higher over the weekend following the attacks, with Brent currently sitting at $108.20 and US Oil at $98.70.

However, we did see confirmation that Oman and Iran have come to an agreement on shipping routes through the Strait, with both sides due in Muscat today to sign the agreement. Long term, this should be beneficial in bringing oil prices down, but in the short term, with attacks still taking place on shipping traffic, the effect of this deal may be muted.
The focus this week will squarely be on the FOMC rate announcement on Wednesday. After warm inflation prints last week and hawkish comments from Fed Chair Warsh the week before, as of this morning there is a predicted 86.7% chance of a rate hike despite President Trump's desire for lower rates and Treasury Secretary Bessent's attempts to lower the long-term US bond yields. Whether the FOMC follows through on the rate hike and how the current administration will react will be the central theme of the week.
Forex
The USD has been mounting a minor comeback over the past few days, gaining ground after warm inflation prints last week. The DXY has continued to rise this morning, currently sitting at 99.400 after being as low as 98.600 before Wednesday's PPI print. These moves are still arguably less than we would have expected, having gone from less than a 50% chance of rate hikes to over 85% in a week. The interesting question this week will be how the USD will react to the expected rate hike. Will it continue to gain strength, or is this already priced in, and can we actually expect some USD weakness in the second half of the week?

The USD/JPY could be an interesting pair to watch as this plays out, as it has once again failed to break below the 153.000 level. On top of the FOMC meeting on Wednesday, we also have the BoJ meeting overnight on Thursday night, meaning this week could be very consequential for this pair in particular. A move below the 153.000 could signal a significant continuation lower, so it will be a key level to watch this week.

With all focus currently on the USD, the other major currencies have been relatively quiet. The CAD has been reacting to fluctuations in oil prices, struggling on Friday but recovering today, while the EUR and GBP have been relatively flat.
Indices
All three major indices have gapped lower over the weekend, in large part due to comments made by a number of the major CEOs of AI companies. It began with Anthropic CEO Dario Amodei, who posted an essay titled 'We Must Pace the Frontier', where he detailed how he felt it necessary to slow the pace of AI growth, to put safety before speed, and that building too fast was reckless. This was swiftly supported by OpenAI CEO Sam Altman, xAI's CEO Elon Musk, Google DeepMind's Demis Hassabis, and Hugging Face's Clement Delangue.
The Nasdaq was the hardest hit, being the one most reliant on tech stocks, with the NAS100 gapping 1% and continuing to fall this morning. The S&P also fell by 0.6%, whilst the least tech-reliant Dow Jones fell by 0.1%.
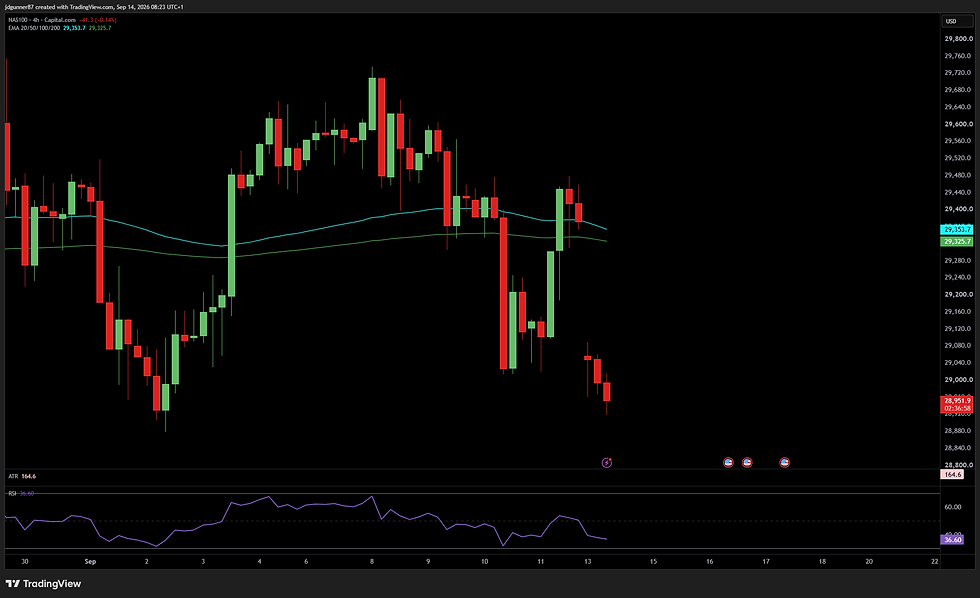
The sentiment towards Amodei's comments was not overwhelmingly in one direction, however. The CEOs of both Microsoft and Meta both disagreed with the assessment, marking an interesting divergence. The companies providing the capex do not want to slow down, while the labs doing the model development want to slow down. An interesting development in the spender-vs-supplier framework we had been looking at previously within the AI sector.
Precious Metals
Both Gold and Silver gapped slightly lower over the weekend and have been struggling today, with Gold down 0.84% at $4,310 and Silver down 1.78% at $63.36. Both metals, as stated before, have not struggled as much as had been expected after last week's
movements in FOMC expectations.

They have struggled today on USD strength, but my conviction remains that there is far more room to move higher than room to move lower. With regards to things that can negatively affect metals - rate hikes, Middle East escalation, higher oil prices - these have all largely happened already and so have already been priced in. If we see the FOMC hold rates unexpectedly, or a de-escalation in the Middle East, for example, there is potentially a lot of upside for the metals.
This Week's Market Drivers
CAD CPI, Today, 1:30pm UK time - A key metric for the CAD market, which will affect the BoC's rates decision moving forward.
GBP CPI, 15th September - Similar to the CAD event the day before, this will affect the BoE's decision-making, but with a more immediate effect as the BoE's decision is later this week.
USD FOMC interest rate decision, Wednesday 16th September - A hike is around 85% priced. After a hot core CPI and hot annual PPI, the decision looks close to settled so the guidance is what matters.
NZD GDP, 16th September - A useful metric to assess the New Zealand economy moving forward.
GBP interest rate decision, 17th September - The BoE is expected to hold, as always the guidance around it and any surprise in the vote-split is likely to be the market movers for GBP.
JPY interest rate decision, 18th September - A 25bp hike to 1.25% is fully priced, with USD/JPY sitting on 153.000.
Comments